CGT Property Valuations

A clear valuation for the date that matters

RPM arranges independent property valuations for Capital Gains Tax purposes, providing a clear, evidence-based assessment of your property's market value at the relevant date.

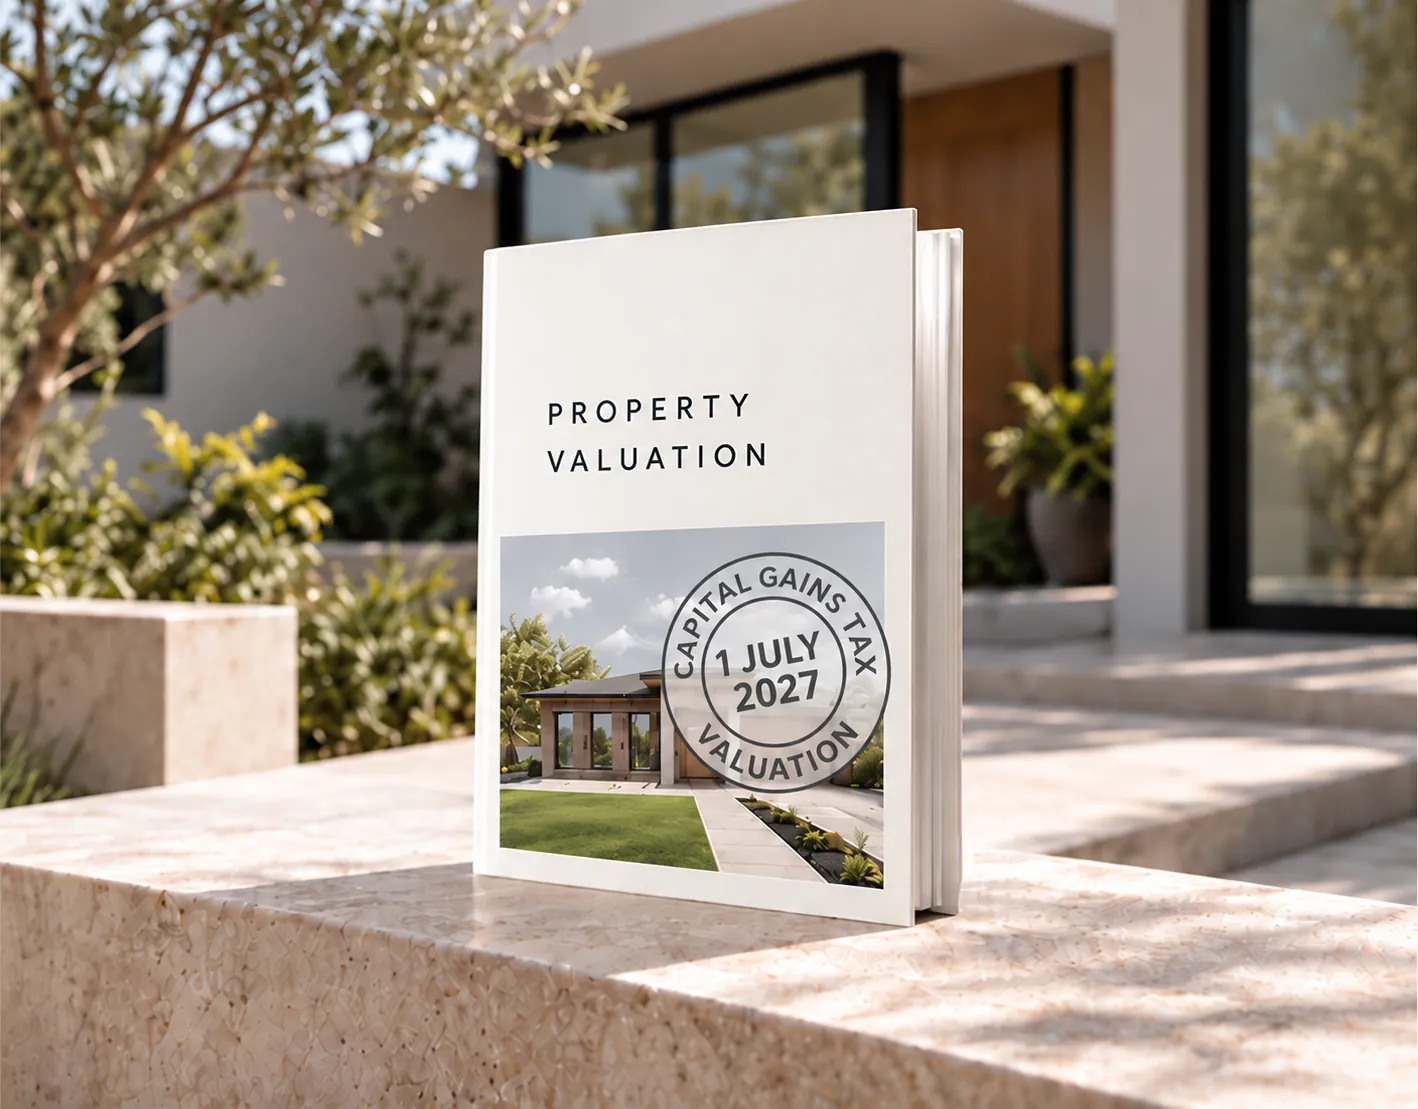
Property valuation booklet for CGT transition date planning

Planning for the 1 July 2027 CGT changes?

Knowing what your property is worth at the relevant date could make a significant difference when calculating Capital Gains Tax.

An independent valuation provides a property-specific assessment based on market evidence, rather than relying solely on a general formula.

RPM can arrange a valuation prepared by a qualified valuer, giving your accountant reliable information to help assess your CGT position.

YOUR PROPERTY'S VALUE AT

1 JULY 2027

A DATE WORTH PLANNING FOR

Two common approaches

There are different ways to establish a cost base for CGT purposes. The most appropriate method depends on your individual circumstances.

Independent market valuation

A valuation of the property's market value immediately before 1 July 2027, prepared by a qualified, independent valuer.

  • Provides an objective, supportable market value
  • Prepared by a qualified, independent valuer
  • May be appropriate for some property owners
Apportioning method

A method that allocates part of the property's cost base to the period before 1 July 2027 based on the increase in value over time.

  • Uses the property's purchase price and growth in value
  • May be suitable in certain circumstances
  • Your accountant can confirm if this approach is appropriate

CGT Transition • Property Example

Why the 1 July 2027 valuation matters

A well-supported market value may improve the tax treatment of pre-transition growth.

Property Snapshot

Purchased

1 Jul 2018

Purchase Price

$650,000

Valuation Date

1 Jul 2027

Independent Value*

$980,000

Future Sale

1 Jul 2032 / $1,200,000

Potential Tax Advantage

The $980,000 market value is $16,121 above the draft apportionment estimate.

That could place more growth in the pre-1 July 2027 period, where the 50% CGT discount may apply if eligible.

Value Difference

+$16,121

How the transition value changes the split

Independent market valuation

Value at 1 Jul 2027
$980,000
Pre-transition gain
$330,000
After assumed 50% discount
$165,000
Post-transition gain, before CPI indexation
$220,000

Higher transition value = more gain in the earlier period

Treasury draft apportionment method

Estimated value at 1 Jul 2027
$963,879
Pre-transition gain
$313,879
After assumed 50% discount
$156,940
Post-transition gain, before CPI indexation
$236,121

Same total gain; a different transition split

Total nominal gain • both methods

$1,200,000 - $650,000 = $550,000

The value affects how the gain is split—not the total nominal gain.

Tax savings are not quantified here. Outcomes depend on eligibility, CPI, tax rates, cost-base adjustments and final rules. *Independent value is an illustrative assumption.

Simplified illustration only. Assumes $650,000 is the relevant cost base and a 50% discount applies to pre-transition gains. Treasury's apportionment method was published as an exposure draft.

Our Partners

Trusted by Australian businesses and industry partners

Working with trusted professionals and businesses across the property industry.

  • Barry Plant logo
  • Century 21 On Duporth logo
  • Coastal logo
  • Cohen Handler logo
  • Harcourts Joondalup logo
  • Harcourts Mandurah logo
  • Housemark logo
  • Magain logo
  • Mcgrath logo
  • MTS Accountants Pty Ltd logo
  • National Property Buyers logo
  • Ouwens Casserly logo
  • Plum Property logo
  • Ray White Norwood logo
  • Ray White logo
  • Southside Tax Services logo
  • Turner Real Estate logo
  • UFinancial logo

CGT property valuations

Questions about CGT valuations?

Understand your valuation options and what may be right for your property.

A practical option for many properties

A desktop valuation uses available property information and market evidence, without a site visit.

Talk with RPM
What is a CGT valuation?

A CGT valuation is an independent assessment of a property's market value at a specified date. It can help support the value used when calculating a capital gain.

When might I need a CGT valuation?

You may need one when selling a property, changing how it is used or establishing its value at a particular date. Your accountant can advise what applies to your circumstances.

Why is the valuation date important?

The valuation needs to reflect the property and market at the date relevant to your circumstances. Information about the property at that time can help support the assessment.

What valuation options are available?

A CGT valuation can be completed as a desktop valuation or with a full property inspection. A desktop valuation may suit many residential properties. RPM can discuss your property and help determine which option is appropriate.

What is a desktop valuation?

A desktop valuation is prepared by a qualified valuer without visiting the property. The valuer considers available property information, market data and comparable sales.

Do I need to arrange access for a desktop valuation?

No. A desktop valuation doesn't require a site visit or internal access. You'll provide the valuer with details about the property and any relevant improvements or features.

Is a desktop valuation suitable for my property?

It may suit a straightforward property where reliable information and comparable sales are available. A full inspection may be more appropriate for a unique, extensively renovated or higher-value property, or where important details can't be confirmed from available information.

What information will the valuer need?

The valuer will typically need the property address, owner details and information about renovations, extensions or other features that may affect value. Plans, approvals and photographs can also help.

Will the ATO accept a desktop valuation?

The ATO doesn't automatically accept or reject a valuation based only on whether it was completed as a desktop assessment or a full inspection. It needs to be objective, evidence-based and appropriate for the property and valuation date. RPM can discuss whether a desktop valuation may suit your property.